Table of Contents
What Is Working Capital?
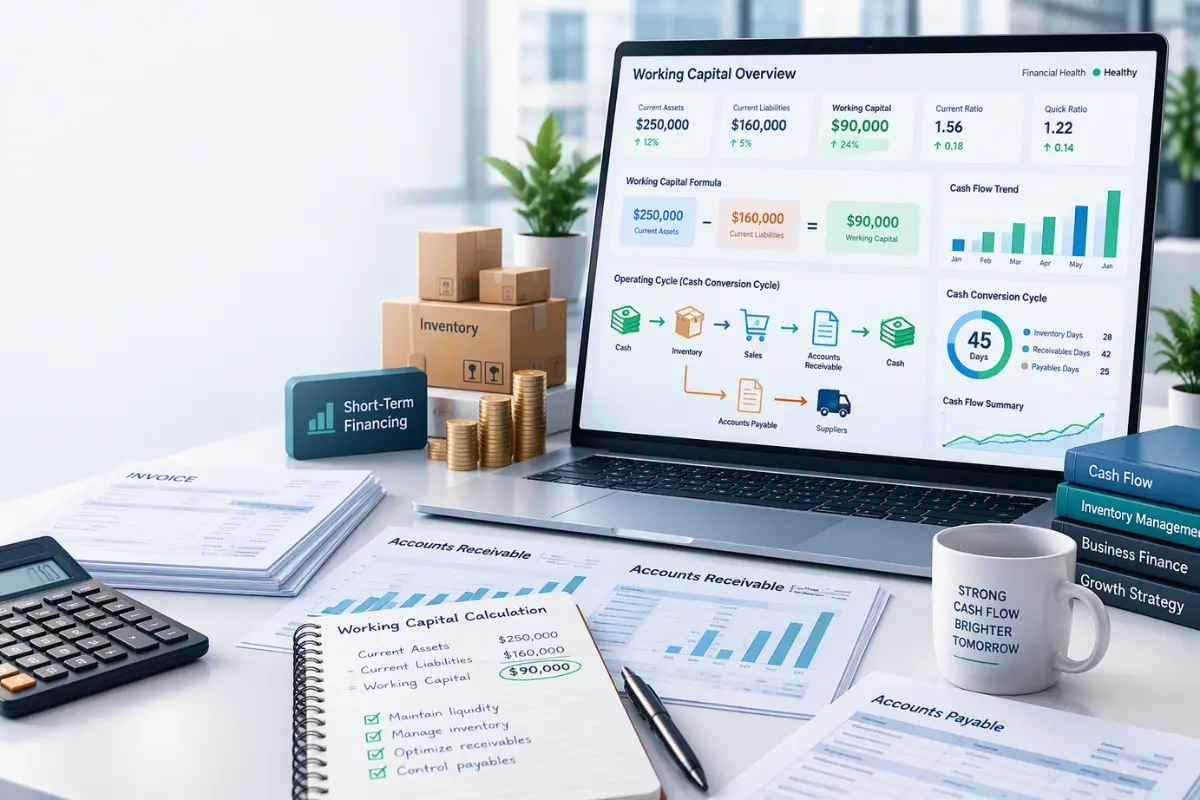
Working capital is the amount of short-term financial resources a business has available to support its day-to-day operations.
The simplest formula is:
Working Capital = Current Assets − Current Liabilities
Current assets are assets expected to be converted into cash or used within the normal operating cycle, while current liabilities are obligations that generally need to be paid in the short term.
For example, suppose a business has:
- Cash: $25,000
- Accounts receivable: $40,000
- Inventory: $35,000
- Accounts payable: $30,000
- Short-term obligations: $15,000
Current assets:
$25,000 + $40,000 + $35,000 = $100,000
Current liabilities:
$30,000 + $15,000 = $45,000
Working capital:
$100,000 − $45,000 = $55,000
The business therefore has $55,000 of net working capital under these assumptions.
Understanding working capital is essential because a profitable business can still experience financial pressure if it does not have enough cash available to pay short-term obligations.
Why Working Capital Matters
Working capital supports the normal operating cycle of a business.
Businesses often need to pay expenses before receiving cash from customers.
For example:
- A company purchases inventory.
- The inventory is stored or processed.
- The product is sold.
- The customer receives an invoice.
- The customer pays later.
- The business finally receives the cash.
During this cycle, money can be tied up in inventory and accounts receivable.
At the same time, the company may need to pay suppliers, employees, rent, taxes, and other expenses.
Effective cash flow management helps ensure that sufficient liquidity is available throughout this process.
Working capital analysis can help businesses:
- Maintain adequate cash reserves
- Pay suppliers on time
- Manage inventory
- Control receivables
- Plan short-term financing
- Identify liquidity problems
- Support business growth
- Reduce unnecessary financing costs
Understanding Current Assets
Current assets are short-term resources that can generally be converted into cash or consumed within the business’s normal operating cycle.
Common examples include:
Cash and Cash Equivalents
Cash is the most immediately liquid current asset.
It can be used to pay:
- Suppliers
- Employees
- Rent
- Utilities
- Taxes
- Debt obligations
- Other operating expenses
Accounts Receivable
Accounts receivable represents money owed by customers for goods or services that have already been provided.
For example, if a business sells $20,000 of products on credit, it may record $20,000 as accounts receivable until customers pay.
Although receivables are generally considered current assets, they are not the same as cash.
A company with large receivables may appear financially strong on paper while having limited cash available.
Inventory
Inventory includes products and materials held for sale or production.
Examples include:
- Raw materials
- Work in progress
- Finished goods
- Merchandise
Inventory contributes to working capital, but it may take time to convert into cash.
This makes inventory management an important part of working capital planning.
Understanding Current Liabilities
Current liabilities are short-term obligations that a business expects to pay within the relevant short-term period.
Examples include:
- Accounts payable
- Short-term loans
- Accrued expenses
- Taxes payable
- Payroll obligations
- Current portions of long-term debt
Accounts Payable
Accounts payable represents amounts owed to suppliers and vendors.
For example, if a company purchases $15,000 of inventory on credit, it may record $15,000 as accounts payable until the supplier is paid.
Managing payment timing is important because paying suppliers too early can reduce available cash, while paying too late may damage supplier relationships or result in penalties.
How to Calculate Working Capital
The basic calculation is straightforward:
Working Capital = Current Assets − Current Liabilities
Suppose:
- Cash = $30,000
- Accounts receivable = $45,000
- Inventory = $25,000
- Other current assets = $5,000
Total current assets:
$30,000 + $45,000 + $25,000 + $5,000 = $105,000
Now assume:
- Accounts payable = $35,000
- Short-term debt = $15,000
- Other current liabilities = $5,000
Total current liabilities:
$35,000 + $15,000 + $5,000 = $55,000
Working capital:
$105,000 − $55,000 = $50,000
The company has $50,000 of positive net working capital.
What Does Positive or Negative Working Capital Mean?
Positive working capital generally means current assets exceed current liabilities.
Negative working capital occurs when:
Current Assets < Current Liabilities
Negative working capital is not automatically a sign of financial failure. Some business models can operate successfully with negative working capital because they receive customer payments before they need to pay suppliers or incur certain costs.
However, for many businesses, persistent negative working capital can create liquidity pressure.
The meaning of working capital should therefore be considered in the context of:
- Industry
- Business model
- Payment terms
- Inventory requirements
- Seasonality
- Operating cycle
- Supplier relationships
- Customer payment behavior
Working Capital Ratio
The working capital ratio, also known as the current ratio, compares current assets with current liabilities.
The formula is:
Working Capital Ratio = Current Assets ÷ Current Liabilities
Using the previous example:
$105,000 ÷ $55,000 = 1.91
A ratio of 1.91 means the business has approximately $1.91 of current assets for every $1 of current liabilities.
The ratio provides another way to evaluate short-term business liquidity.
However, a higher ratio is not automatically better. Excessive current assets can sometimes indicate that cash is sitting idle or too much capital is tied up in inventory or receivables.
Liquidity Ratio and Business Liquidity
A liquidity ratio helps evaluate whether a business can meet its short-term obligations.
The current ratio is one common liquidity measure.
Another is the quick ratio:
Quick Ratio = (Cash + Short-Term Investments + Accounts Receivable) ÷ Current Liabilities
The quick ratio excludes inventory because inventory generally takes longer to convert into cash.
For example:
- Cash = $30,000
- Accounts receivable = $45,000
- Current liabilities = $55,000
Quick ratio:
($30,000 + $45,000) ÷ $55,000
= 1.36
This provides additional information about the company’s ability to meet short-term obligations using more liquid assets.
Estimating Working Capital Requirements
Calculating current working capital tells you where the business stands today.
Estimating working capital requirements asks a different question:
How much working capital will the business need in the future?
A practical estimate should consider expected:
- Sales
- COGS
- Inventory requirements
- Customer payment periods
- Supplier payment periods
- Operating expenses
- Seasonal fluctuations
- Growth
- Cash reserves
A business that expects rapid growth may need additional working capital even if its current financial position is healthy.
Why?
Because growth can require more:
- Inventory
- Employees
- Marketing
- Production
- Receivables
- Supplier purchases
The Cash Conversion Cycle
The cash conversion cycle measures how long cash is tied up in the operating process.
It is commonly expressed as:
Cash Conversion Cycle = Inventory Days + Receivable Days − Payable Days
The three components are:
Inventory Days
This measures approximately how long inventory remains in the business before being sold.
Accounts Receivable Days
This measures how long customers generally take to pay.
Accounts Payable Days
This measures how long the business takes to pay suppliers.
For example:
- Inventory days = 40
- Receivable days = 30
- Payable days = 25
Cash conversion cycle:
40 + 30 − 25 = 45 days
The business therefore has approximately 45 days between paying for resources and collecting the related cash, under the assumptions used.
Working Capital and Operating Cash Flow
Operating cash flow measures the cash generated or consumed by a company’s normal business operations.
Profit and operating cash flow are not necessarily the same.
A company can report a profit while experiencing weak cash flow if customers have not yet paid their invoices or if substantial funds have been invested in inventory.
For example, imagine a company makes a $50,000 sale on credit.
The sale may increase accounting revenue and profit, but the company does not receive cash until the customer pays.
This is why working capital management and operating cash flow should be analyzed together.
Accounts Receivable and Working Capital
Accounts receivable can significantly affect working capital.
Suppose a business has $200,000 in annual sales but allows customers to pay after 90 days.
A substantial amount of cash can become tied up in receivables.
Businesses can improve receivables management by:
- Setting clear payment terms
- Invoicing promptly
- Monitoring overdue accounts
- Offering convenient payment methods
- Following up on unpaid invoices
- Evaluating customer creditworthiness
Reducing the time between invoicing and payment can improve cash availability.
Accounts Payable and Working Capital
Accounts payable can also influence cash flow.
If suppliers provide 30-day payment terms, the business may be able to sell products and collect some customer payments before the supplier invoice becomes due.
Businesses can improve payable management by:
- Negotiating reasonable payment terms
- Paying invoices according to agreed terms
- Taking advantage of legitimate early-payment discounts
- Avoiding unnecessary early payments
- Maintaining good supplier relationships
The objective is not simply to delay payments. It is to manage payment timing responsibly while maintaining reliable supplier relationships.
Inventory Management and Working Capital
Inventory can represent a significant investment of working capital.
Excess inventory can create several problems:
- Cash becomes tied up
- Storage costs increase
- Products may become obsolete
- Insurance costs can increase
- Discounts may be required to clear stock
On the other hand, insufficient inventory can lead to:
- Stockouts
- Lost sales
- Customer dissatisfaction
- Production delays
Effective inventory management attempts to balance availability with the amount of capital invested in stock.
Useful measures include:
- Inventory turnover
- Days inventory outstanding
- Reorder points
- Safety stock
- Economic order quantity
- Stockout rates
Seasonal Working Capital Requirements
Some businesses require substantially more working capital during particular periods.
Examples include:
- Retail businesses before holiday seasons
- Agriculture businesses before harvest
- Tourism businesses during peak seasons
- Construction companies during major projects
- Businesses preparing for promotional campaigns
A company may therefore have sufficient working capital during one month and experience a temporary shortage during another.
Working capital estimates should consider these seasonal patterns instead of relying only on annual averages.
Working Capital and Short-Term Financing
When internal working capital is insufficient, a business may consider short-term financing.
Possible sources can include:
- Business lines of credit
- Short-term loans
- Supplier credit
- Invoice financing
- Overdraft facilities
- Revolving credit arrangements
Short-term financing can help bridge temporary cash gaps, but it also introduces interest costs and repayment obligations.
Before using financing, businesses should understand why the cash shortage exists.
If the problem is caused by slow receivables, excessive inventory, or structurally low margins, financing alone may not solve the underlying issue.
A Practical Working Capital Forecast
A simple forecast can be created using expected operating assumptions.
Suppose a business expects:
- Monthly sales: $100,000
- Average receivables: $40,000
- Inventory: $30,000
- Cash reserve: $20,000
- Accounts payable: $35,000
- Other current liabilities: $10,000
Current assets:
$40,000 + $30,000 + $20,000 = $90,000
Current liabilities:
$35,000 + $10,000 = $45,000
Estimated working capital:
$90,000 − $45,000 = $45,000
The business could then test different scenarios.
For example:
Scenario 1: Sales increase
Higher sales may require additional inventory and receivables.
Scenario 2: Customers pay faster
Lower receivables can release cash.
Scenario 3: Suppliers extend payment terms
Higher accounts payable may temporarily reduce the amount of working capital required.
Scenario 4: Inventory turnover improves
Less cash may be tied up in inventory.
Scenario analysis can make working capital planning much more useful than relying on one static number.
How to Improve Working Capital
Businesses can often improve working capital without simply raising additional financing.
Accelerate Customer Payments
Shortening the collection cycle can increase available cash.
Improve Inventory Turnover
Identify slow-moving inventory and adjust purchasing and production accordingly.
Negotiate Supplier Terms
Reasonable payment terms can help align supplier payments with customer collections.
Monitor Cash Flow Regularly
Cash flow forecasts can identify potential shortages before they become urgent.
Maintain an Appropriate Cash Reserve
A cash buffer can provide protection against unexpected expenses or temporary revenue declines.
Review Working Capital Metrics
Monitor:
- Current ratio
- Quick ratio
- Receivable days
- Inventory days
- Payable days
- Cash conversion cycle
- Operating cash flow
Using a Working Capital Calculator
A Working Capital Calculator can simplify the estimation process.
Typical inputs can include:
- Cash and cash equivalents
- Accounts receivable
- Inventory
- Other current assets
- Accounts payable
- Short-term debt
- Other current liabilities
- Annual sales
- COGS
- Receivable days
- Inventory days
- Payable days
- Industry type
Potential outputs include:
- Net working capital
- Current ratio
- Quick ratio
- Cash conversion cycle
- Working capital turnover
- Cash coverage
- Industry comparison
- Seasonal working capital requirements
These metrics provide a broader picture than the basic working capital formula alone.
Common Working Capital Mistakes
Confusing Profit With Cash
A profitable business can still have cash-flow problems.
Holding Too Much Inventory
Excess inventory can tie up capital unnecessarily.
Allowing Receivables to Grow
Slow customer payments can create liquidity pressure.
Paying Suppliers Too Early
Paying well before invoices are due can reduce available cash unnecessarily.
Ignoring Seasonality
Annual averages may hide temporary working capital shortages.
Relying Entirely on Financing
Debt can provide liquidity, but it does not necessarily solve inefficient working capital processes.
Using Industry Benchmarks Without Context
Working capital requirements vary significantly by business model and industry.
Frequently Asked Questions
What is the basic working capital formula?
The basic formula is:
Working Capital = Current Assets − Current Liabilities
What is a good working capital ratio?
There is no single ratio that is appropriate for every business. The appropriate level depends on the company’s industry, operating cycle, payment terms, inventory requirements, and business model.
Is positive working capital always good?
Positive working capital generally means current assets exceed current liabilities, but excessive working capital can also indicate that cash is inefficiently tied up in inventory or receivables.
How does inventory affect working capital?
Inventory is a current asset, so increasing inventory generally increases working capital. However, inventory also uses cash and may take time to convert back into cash.
How do accounts receivable affect working capital?
Accounts receivable increase current assets, but they represent money owed rather than cash already collected. Slow collections can create liquidity pressure.
How does the cash conversion cycle affect working capital?
A longer cash conversion cycle generally means cash remains tied up in operations for longer. Improving inventory turnover, collecting receivables faster, or managing supplier terms can shorten the cycle.
Can a growing business need more working capital?
Yes. Growth can increase inventory, receivables, payroll, production, and other operating requirements before additional sales are converted into cash.