Table of Contents
What Are Profit Margins?
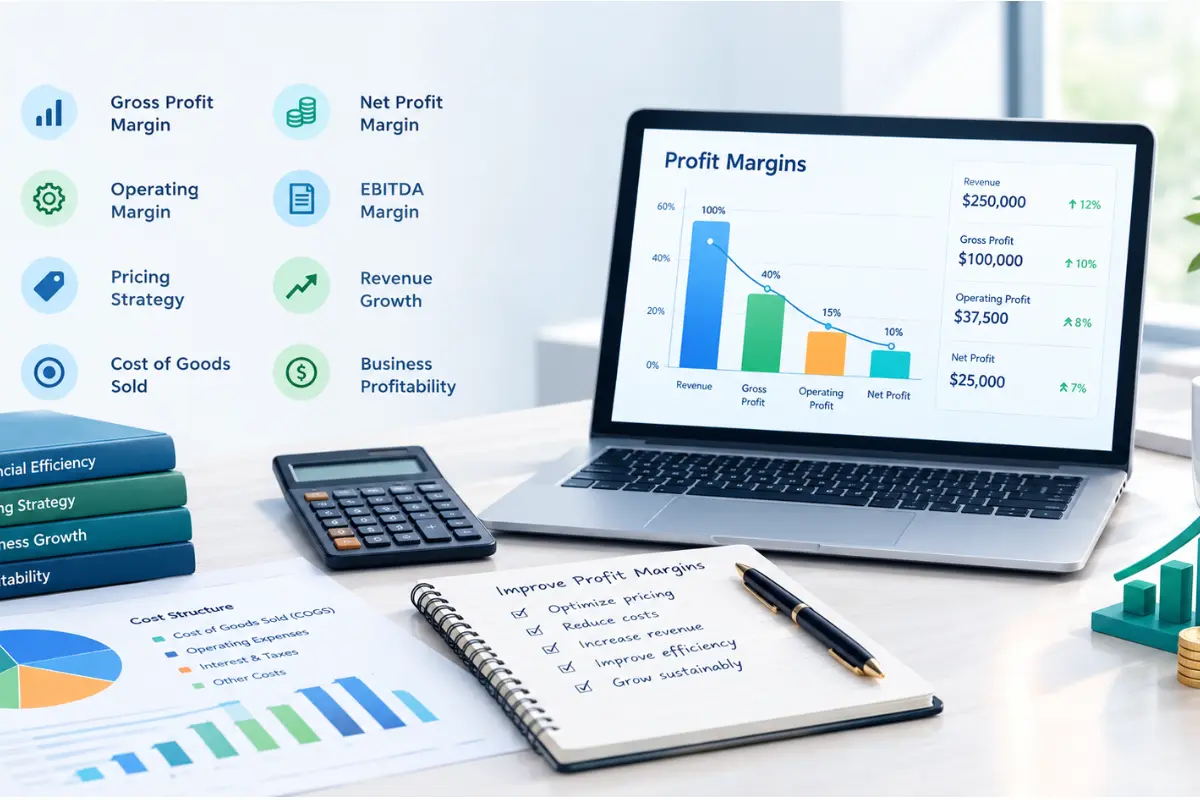
Profit margins measure how much money a business keeps as profit after accounting for its costs. They are usually expressed as a percentage of revenue.
For example, if a business generates $100,000 in revenue and earns $20,000 in net profit, its net profit margin is 20%.
Net Profit Margin = Net Profit ÷ Revenue × 100
Profit margins are useful because revenue alone does not tell you how efficiently a business operates. Two companies can generate the same revenue while having very different levels of profitability.
A business with $1 million in sales and $50,000 in profit has a very different financial position from one with $1 million in sales and $250,000 in profit.
Understanding profit margins helps business owners evaluate pricing, costs, operational performance, and overall business profitability.
Why Profit Margins Matter
Profit margins provide a simple way to connect sales with financial performance.
They can help businesses:
- Evaluate profitability
- Monitor operating costs
- Review pricing decisions
- Identify inefficient expenses
- Compare performance over time
- Support financial planning
- Evaluate revenue growth
- Measure operational improvements
- Understand return on investment
- Make better budgeting decisions
Profit margins can also reveal problems that may not be obvious from revenue growth alone.
For example, a company may increase revenue by 30% while its profit margin falls because production, marketing, payroll, or distribution costs have increased even faster.
This is why revenue growth and profitability should generally be analyzed together.
The Three Main Types of Profit Margins
Businesses commonly use three major profitability measures:
- Gross profit margin
- Operating profit margin
- Net profit margin
Each measures profitability at a different stage of the income statement.
Gross Profit Margin
Gross profit is revenue remaining after deducting the cost of goods sold (COGS).
The basic formula is:
Gross Profit = Revenue − Cost of Goods Sold
The gross profit margin is:
Gross Profit Margin = Gross Profit ÷ Revenue × 100
For example:
- Revenue: $100,000
- COGS: $60,000
- Gross profit: $40,000
Gross profit margin:
$40,000 ÷ $100,000 × 100 = 40%
A 40% gross margin means the business retains $0.40 from each dollar of revenue after covering its direct costs.
Operating Profit Margin
Operating profit accounts for operating expenses after gross profit.
These expenses can include:
- Salaries
- Rent
- Marketing
- Utilities
- Administrative expenses
- Software
- Insurance
- Professional services
The formula is:
Operating Profit = Gross Profit − Operating Expenses
Then:
Operating Margin = Operating Profit ÷ Revenue × 100
Operating margin provides insight into how efficiently the core business operates before considering certain non-operating items, such as interest and taxes.
Net Profit Margin
Net profit represents the amount remaining after the business accounts for all relevant expenses.
Depending on the accounting structure, these may include:
- COGS
- Operating expenses
- Interest
- Taxes
- Depreciation
- Other expenses
The formula is:
Net Profit Margin = Net Profit ÷ Revenue × 100
For example:
- Revenue: $100,000
- Net profit: $15,000
Net profit margin:
$15,000 ÷ $100,000 × 100 = 15%
This means the business keeps $0.15 of every dollar of revenue as net profit.
Understanding EBITDA Margin
EBITDA stands for earnings before interest, taxes, depreciation, and amortization.
EBITDA is often used to evaluate operating performance before these specific financial items.
The basic calculation is:
EBITDA Margin = EBITDA ÷ Revenue × 100
For example:
- Revenue: $500,000
- EBITDA: $100,000
EBITDA margin:
$100,000 ÷ $500,000 × 100 = 20%
EBITDA margin can be useful when comparing operating performance, particularly when businesses have different financing structures or depreciation profiles.
However, EBITDA is not the same as net profit and should not be treated as a substitute for cash flow or final profitability.
How to Calculate Profit Margins
Calculating profit margins requires two basic figures:
- Revenue
- The relevant profit measure
For gross margin, use gross profit.
For operating margin, use operating profit.
For net margin, use net profit.
Example Calculation
Suppose a business has:
- Revenue: $200,000
- COGS: $120,000
- Operating expenses: $50,000
- Interest and taxes: $10,000
Gross profit:
$200,000 − $120,000 = $80,000
Gross profit margin:
$80,000 ÷ $200,000 × 100 = 40%
Operating profit:
$80,000 − $50,000 = $30,000
Operating margin:
$30,000 ÷ $200,000 × 100 = 15%
Net profit:
$30,000 − $10,000 = $20,000
Net profit margin:
$20,000 ÷ $200,000 × 100 = 10%
The three margins tell different parts of the same financial story.
Profit Margins vs Markup
Profit margin and markup are often confused, but they are not the same.
Suppose a product costs $60 and sells for $100.
Profit:
$100 − $60 = $40
Profit margin:
$40 ÷ $100 × 100 = 40%
Markup:
$40 ÷ $60 × 100 = 66.67%
Therefore, a 66.67% markup produces a 40% margin in this example.
Understanding this distinction is particularly important when developing a pricing strategy.
The Relationship Between COGS and Profit Margins
Cost of goods sold has a direct impact on gross profit margins.
If selling prices remain unchanged while COGS increases, gross margin decreases.
For example:
Original situation
- Selling price: $100
- COGS: $60
- Gross profit: $40
- Gross margin: 40%
After cost increase
- Selling price: $100
- COGS: $70
- Gross profit: $30
- Gross margin: 30%
A 10-point reduction in gross margin can significantly affect overall profitability when sales volumes are large.
Businesses should therefore monitor supplier pricing, production costs, shipping, materials, labor, and other direct costs.
Profit Margins and Pricing Strategy
Pricing is one of the most direct ways to influence profit margins.
A pricing strategy should consider:
- Product costs
- Desired margin
- Customer demand
- Competitor pricing
- Perceived customer value
- Market positioning
- Sales volume
- Discounts
- Distribution costs
Simply increasing prices does not always improve profitability if the higher price causes a significant reduction in sales volume.
Similarly, reducing prices can increase sales but potentially reduce the contribution from each sale.
The goal is to understand how price, volume, and costs interact.
How Revenue Growth Affects Profit Margins
Revenue growth does not automatically mean improved profitability.
Consider a business that grows from $100,000 to $150,000 in revenue.
If net profit grows from $10,000 to $12,000, the business has higher absolute profit but a lower margin.
Before:
$10,000 ÷ $100,000 = 10%
After:
$12,000 ÷ $150,000 = 8%
Revenue increased by 50%, but the net profit margin decreased from 10% to 8%.
This distinction is important because sustainable growth generally requires attention to both sales and the cost structure supporting those sales.
Improving Financial Efficiency
Improving financial efficiency means generating stronger financial results from available resources.
Several approaches can improve margins.
Reduce Unnecessary Costs
Review recurring expenses and identify costs that do not contribute meaningfully to revenue or operations.
Examples include:
- Unused software subscriptions
- Excessive administrative expenses
- Inefficient processes
- Unnecessary inventory
- Expensive supplier contracts
Improve Operational Efficiency
Automation, better workflows, employee training, and improved inventory management can reduce operating costs.
Negotiate Supplier Costs
Lower COGS can improve gross margins when selling prices remain stable.
Businesses may negotiate:
- Bulk discounts
- Better payment terms
- Shipping rates
- Contract pricing
- Supplier agreements
Reduce Waste
Waste in materials, inventory, labor, time, and energy can reduce profitability.
Identifying these losses can improve margins without necessarily increasing prices.
Profit Margins and Business Profitability
Profit margins are one component of business profitability, but they should not be considered in isolation.
A business can have a high margin but relatively low sales volume.
Another business can operate with lower margins but generate substantial total profits because of its scale.
For example:
Business A
- Revenue: $100,000
- Net margin: 30%
- Net profit: $30,000
Business B
- Revenue: $1,000,000
- Net margin: 8%
- Net profit: $80,000
The examples show why both margin percentages and absolute profit matter.
Profit Margins and Return on Investment
Return on investment (ROI) measures the return generated relative to an investment.
Profit margins and ROI answer different questions.
Profit margin asks:
How much profit is generated from revenue?
ROI asks:
How much return is generated relative to the investment?
For example, a business may have a 15% net profit margin but require a very large investment to generate that revenue.
Another business may have a lower margin but require significantly less capital.
Therefore, businesses evaluating investments should consider margins alongside ROI, cash flow, capital requirements, and risk.
How to Improve Profit Margins
Improving profit margins generally involves increasing revenue, reducing costs, or improving the relationship between the two.
Increase Prices Carefully
If customers remain willing to buy at a higher price, increasing prices can increase the contribution from each sale.
Reduce Variable Costs
Negotiate supplier contracts, optimize production, reduce waste, and improve logistics.
Improve Product Mix
Some products and services may have significantly higher margins than others.
Analyzing profitability by product can help businesses understand which offerings contribute most to overall profit.
Increase Customer Value
Additional services, premium versions, bundles, subscriptions, and complementary products can increase revenue per customer.
Control Operating Expenses
Review salaries, rent, technology, marketing, administrative expenses, and other overhead regularly.
Profit Margin Analysis by Product
Looking only at total company margins can hide differences between individual products.
Imagine a business sells three products:
- Product A: 20% margin
- Product B: 45% margin
- Product C: 10% margin
If Product C represents most of the company’s sales, the overall margin may remain relatively low even though some products are highly profitable.
Product-level margin analysis can help management evaluate:
- Pricing
- Discounts
- Product mix
- Inventory decisions
- Marketing allocation
- Sales priorities
Profit Margins and Business Growth
Growth can create both opportunities and challenges for profitability.
As sales increase, a company may benefit from economies of scale. Certain fixed expenses may be spread across a larger revenue base.
However, growth can also require:
- More employees
- Larger facilities
- More inventory
- Higher marketing spending
- Additional technology
- Increased logistics costs
- More working capital
Therefore, businesses should monitor margins during periods of rapid expansion.
A growing company should not assume that higher sales automatically produce better profitability.
Using a Profit Margin Calculator
A profit margin calculator can simplify profitability analysis.
A typical calculator may require:
- Revenue or sales
- Cost of goods sold
- Operating expenses
- Other expenses
- Selling price
- Cost price
- Expected profit margin
- Industry type
It can calculate:
- Gross profit margin
- Operating profit margin
- Net profit margin
- Markup percentage
- Required selling price
- Industry comparison
These calculations can help business owners quickly evaluate different pricing and cost scenarios.
Common Profit Margin Mistakes
Looking Only at Revenue
High revenue does not necessarily mean high profitability.
Confusing Margin With Markup
These percentages use different bases and should not be treated as interchangeable.
Ignoring COGS
Underestimating direct costs can make gross margins appear stronger than they actually are.
Ignoring Operating Expenses
A strong gross margin can still result in a weak net margin if overhead is excessive.
Comparing Different Industries Directly
Profit margins can vary considerably across industries and business models. Comparisons should consider relevant industry and company characteristics.
Focusing on One Period
A single month may not represent normal performance due to seasonality, unusual expenses, or temporary changes in sales.
Frequently Asked Questions
What is a good profit margin?
There is no universal profit margin that applies to every business. Margins vary by industry, business model, pricing structure, scale, competition, and cost structure.
The most useful approach is often to compare a company’s margins with its own historical performance and relevant industry benchmarks.
What is the difference between gross and net profit margin?
Gross profit margin measures profitability after deducting COGS. Net profit margin measures what remains after the relevant operating and non-operating expenses have been accounted for.
Why can revenue increase while profit margin decreases?
Revenue can increase while margins decline if costs increase faster than revenue. Higher payroll, COGS, marketing expenses, discounts, or other operating costs can reduce profitability.
How can a business increase profit margins?
Common approaches include improving pricing, reducing COGS, controlling operating expenses, improving productivity, reducing waste, and increasing the share of higher-margin products or services.
Is EBITDA margin the same as net profit margin?
No. EBITDA excludes interest, taxes, depreciation, and amortization, while net profit accounts for the relevant expenses required to arrive at final profit.