What Is Break-Even Analysis?
Table of Contents
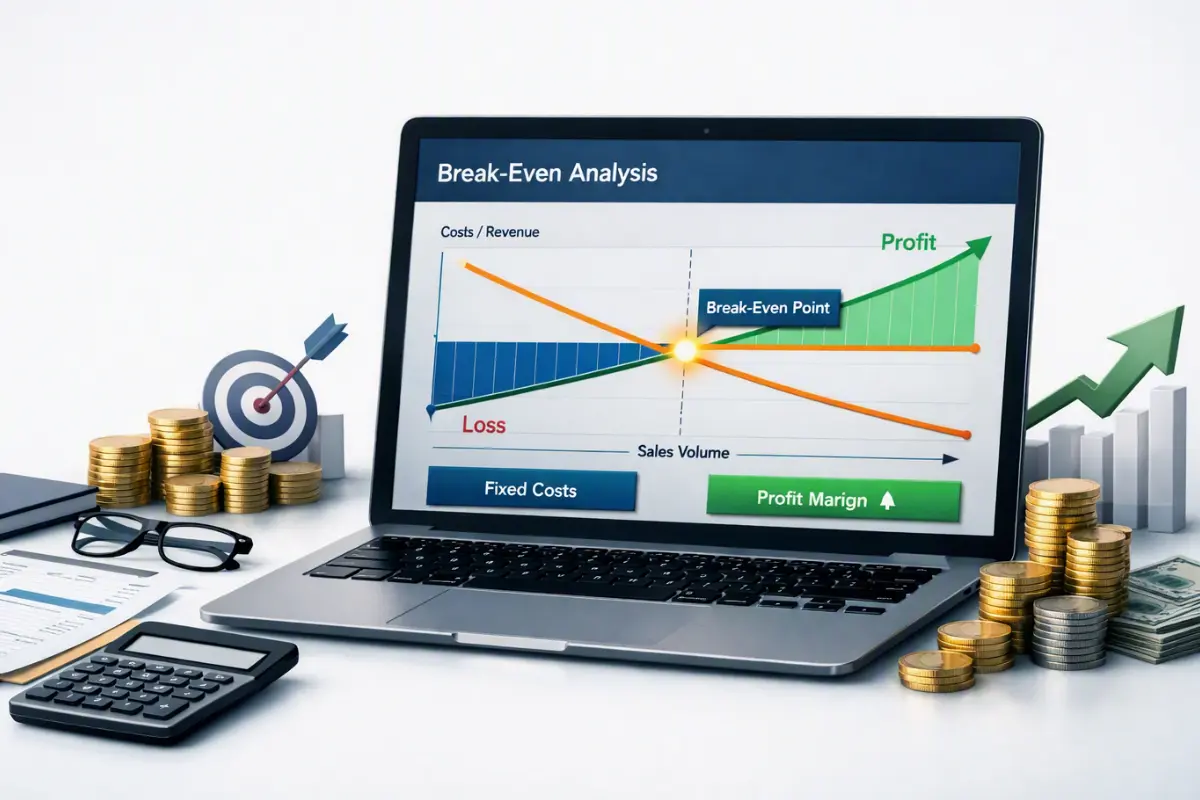
Break-even analysis is a financial planning method used to determine the level of sales a business needs to cover all of its costs. At the break-even point, total revenue equals total costs, meaning the business is neither making a profit nor experiencing a loss.
The concept is simple but extremely useful. By understanding how many products or services must be sold before generating profit, business owners can establish realistic revenue targets, evaluate pricing decisions, and plan future expenses.
The break-even point is especially useful for startups, small businesses, retailers, service providers, and companies evaluating a new product or business model.
In practical terms, break-even analysis answers an important question:
How much do I need to sell before my business starts making money?
Why Break-Even Matters for Business Profitability
A business can generate substantial revenue and still lose money if its costs are too high. Looking only at sales figures does not provide a complete picture of financial performance.
Break-even analysis connects revenue, costs, pricing, and sales volume.
It can help you:
- Set realistic sales targets
- Understand the impact of fixed costs
- Analyze pricing decisions
- Measure the effect of variable costs
- Estimate required sales volume
- Evaluate new products or services
- Plan business expansion
- Improve business profitability
- Support financial forecasting
- Understand financial risk
For example, if your business needs to sell 1,000 units every month just to cover its expenses, that figure becomes an important benchmark for your sales team and management.
Selling below that level may result in a loss, while selling above it can generate operating profit.
Understanding the Key Components of Break-Even Analysis
Several financial concepts work together to determine the break-even point.
Fixed Costs
Fixed costs are expenses that generally remain relatively stable regardless of how many units a business sells.
Examples include:
- Rent
- Salaries
- Insurance
- Software subscriptions
- Accounting fees
- Office expenses
- Equipment depreciation
- Certain administrative expenses
Suppose a business has monthly fixed costs of $10,000. These costs must be covered even if the company sells zero products during the month.
Higher fixed costs generally increase the amount of revenue required to reach break-even.
Variable Costs
Variable costs change according to production or sales volume.
Examples include:
- Raw materials
- Packaging
- Shipping
- Sales commissions
- Payment processing fees
- Direct production labor
- Per-unit manufacturing costs
If it costs $20 to produce and deliver one product, that $20 is a variable cost associated with that sale.
The relationship between fixed costs, variable costs, and selling price is central to break-even analysis.
Selling Price
The selling price is the amount a customer pays for a product or service.
For example:
- Selling price = $50
- Variable cost = $20
The business has $30 available from each sale to contribute toward fixed costs and eventually profit.
This amount is called the contribution margin.
Contribution Margin
The contribution margin is one of the most important concepts in break-even analysis.
It represents the amount remaining from each sale after variable costs are deducted.
Contribution Margin per Unit = Selling Price − Variable Cost per Unit
For example:
- Selling price: $50
- Variable cost: $20
- Contribution margin: $30
Every unit sold contributes $30 toward covering fixed costs.
Once fixed costs have been completely covered, additional contribution margin can contribute to operating profit.
How to Calculate the Break-Even Point
The most common break-even calculation determines the number of units that must be sold.
Break-Even Units Formula
Break-Even Units = Fixed Costs ÷ Contribution Margin per Unit
Since:
Contribution Margin = Selling Price − Variable Cost per Unit
the formula can also be written as:
Break-Even Units = Fixed Costs ÷ (Selling Price − Variable Cost per Unit)
Consider this example:
- Fixed costs = $10,000
- Selling price = $50
- Variable cost per unit = $20
Contribution margin:
$50 − $20 = $30
Break-even units:
$10,000 ÷ $30 = 333.33
Since a business cannot normally sell a fraction of a unit, it would need to sell approximately 334 units to reach break-even.
Break-Even Revenue
You can also calculate the amount of revenue required to reach break-even.
Break-Even Revenue = Break-Even Units × Selling Price
Using the previous example:
334 × $50 = $16,700
Therefore, approximately $16,700 in sales revenue is required to cover the costs under these assumptions.
Break-Even and Profit Margin
Profit margin measures how much of a company’s revenue remains as profit after relevant costs are deducted.
Break-even analysis is closely related to profit margin because pricing and costs determine how quickly a business moves from covering costs to generating profit.
For example, consider two businesses:
Business A
- Selling price: $50
- Variable cost: $40
- Contribution margin: $10
Business B
- Selling price: $50
- Variable cost: $20
- Contribution margin: $30
If both businesses have $10,000 in fixed costs, Business A requires substantially more sales volume to reach break-even.
This illustrates why improving margins can be just as important as increasing sales.
Break-Even Analysis and Revenue Targets
Break-even calculations can be used to establish practical revenue targets.
Instead of asking only:
“How much can we sell?”
management can ask:
“How much must we sell to cover our costs?”
A business can then establish several levels of targets:
- Break-even revenue
- Minimum revenue target
- Target revenue for a desired profit
- Stretch revenue target
For example, if break-even revenue is $20,000 per month, management may establish a target of $30,000 or $35,000 to create a meaningful operating profit buffer.
This makes financial planning more measurable.
Using Break-Even Analysis With a Sales Forecast
A sales forecast estimates future sales based on historical performance, market conditions, customer demand, pricing, seasonality, and other assumptions.
Combining a sales forecast with break-even analysis provides additional insight.
Suppose your forecast estimates:
- Expected sales: 500 units
- Break-even requirement: 334 units
The difference gives you a basic margin of safety.
Margin of Safety = Actual or Expected Sales − Break-Even Sales
In this example:
500 − 334 = 166 units
This means the forecasted sales volume is above the break-even level.
If your sales forecast is below the break-even point, management may need to reconsider pricing, costs, marketing, or sales assumptions.
Break-Even Analysis and Cost-Volume-Profit Analysis
Break-even analysis is an important component of cost-volume-profit analysis, commonly called CVP analysis.
CVP analysis examines the relationship between:
- Sales price
- Sales volume
- Variable costs
- Fixed costs
- Contribution margin
- Profit
Break-even analysis focuses specifically on the point where profit equals zero.
CVP analysis can go further by asking questions such as:
- How many units are needed to generate $10,000 in profit?
- What happens if prices increase by 10%?
- What happens if variable costs increase?
- How would higher rent affect profitability?
- How much additional sales volume is required after hiring more employees?
This makes CVP analysis useful for scenario planning and management decisions.
Operating Leverage and Break-Even Risk
Operating leverage describes how sensitive operating profit is to changes in sales volume, particularly when a business has significant fixed costs.
Businesses with high fixed costs can experience large changes in operating profit when sales change.
For example, imagine a company invests heavily in equipment and facilities. Its fixed costs may be high, but its cost per additional unit may be relatively low.
Once the business passes break-even, additional sales can potentially generate significant operating profit because many fixed costs have already been covered.
However, the opposite can also occur. If sales fall significantly, high fixed costs can increase financial pressure.
This is why break-even analysis is particularly useful when evaluating expansion, new facilities, equipment purchases, or other decisions that increase fixed expenses.
How Pricing Changes the Break-Even Point
Pricing has a direct impact on break-even.
Assume:
- Fixed costs = $10,000
- Variable cost = $20
- Original selling price = $50
Break-even:
$10,000 ÷ ($50 − $20) = 334 units
Now suppose the price increases to $60 while variable costs remain $20.
New contribution margin:
$60 − $20 = $40
New break-even:
$10,000 ÷ $40 = 250 units
The higher price increases the contribution margin and reduces the required sales volume.
However, pricing decisions should also consider customer demand, competition, perceived value, and price sensitivity. A higher price can affect the number of units customers are willing to purchase.
How Reducing Costs Affects Break-Even
Businesses can also lower their break-even point by reducing costs.
Reducing Fixed Costs
If fixed costs fall from $10,000 to $8,000 while the contribution margin remains $30:
$8,000 ÷ $30 = 267 units
The company now needs approximately 267 units instead of 334.
Reducing Variable Costs
Suppose the variable cost falls from $20 to $15.
The new contribution margin becomes:
$50 − $15 = $35
Break-even:
$10,000 ÷ $35 = 286 units
Both strategies can improve the break-even position, although their practical effects depend on the business model.
Break-Even Analysis in Financial Modeling
Break-even calculations are often included in broader financial modeling.
A financial model may combine:
- Revenue assumptions
- Pricing
- Sales volume
- Fixed costs
- Variable costs
- Payroll
- Capital expenditure
- Financing
- Cash flow
- Profit forecasts
Break-even analysis provides one reference point within this larger model.
For startups, it can help estimate when the business might move from operating losses toward profitability.
For established businesses, it can support budgeting, expansion planning, product analysis, and scenario modeling.
Using a Break-Even Calculator
A break-even calculator makes the calculation faster and easier by automatically applying the formulas.
A typical calculator requires four primary inputs:
Fixed Costs
Enter the total fixed costs for the period being analyzed.
Variable Cost per Unit
Enter the variable cost associated with producing or delivering one unit.
Selling Price per Unit
Enter the amount charged to the customer for each unit.
Expected Sales Units
Enter the expected number of units you plan to sell.
The calculator can then estimate:
- Contribution margin
- Contribution margin percentage
- Break-even units
- Break-even revenue
- Expected profit or loss
- Margin of safety
These outputs help connect the theoretical calculation with practical business planning.
Example of a Complete Break-Even Calculation
Consider a business with:
- Fixed costs: $10,000
- Variable cost per unit: $20
- Selling price per unit: $50
- Expected sales: 500 units
Step 1: Calculate Contribution Margin
$50 − $20 = $30
Step 2: Calculate Contribution Margin Percentage
$30 ÷ $50 × 100 = 60%
Step 3: Calculate Break-Even Units
$10,000 ÷ $30 = 333.33
Rounded up:
334 units
Step 4: Calculate Break-Even Revenue
334 × $50 = $16,700
Step 5: Estimate Expected Profit
Expected contribution:
500 × $30 = $15,000
Less fixed costs:
$15,000 − $10,000 = $5,000 expected operating profit
This example demonstrates how break-even analysis can connect sales volume directly to expected profitability.
Common Break-Even Analysis Mistakes
Break-even analysis is useful, but its results depend on the assumptions entered into the calculation.
Using Unrealistic Sales Prices
A theoretical price may produce an attractive break-even point, but customers may not accept that price.
Ignoring Variable Costs
Underestimating variable costs can make the break-even point appear lower than it actually is.
Forgetting Fixed Expenses
Rent, salaries, insurance, subscriptions, and other recurring expenses should be considered where appropriate.
Assuming Costs Never Change
In real businesses, costs can change as production volume increases.
Treating Forecasts as Guaranteed Results
Break-even calculations are based on assumptions. Actual sales, costs, and customer behavior can differ.
Ignoring Seasonality
A business may be profitable annually but still experience periods where sales fall below its break-even level.
Break-Even Analysis for Better Business Decisions
Break-even analysis can be used for more than calculating a single sales number.
Business owners can use it to compare scenarios.
For example:
Scenario 1: Increase price by 10%
Scenario 2: Reduce variable cost by 10%
Scenario 3: Reduce fixed expenses
Scenario 4: Increase marketing investment
Scenario 5: Launch a new product
Each scenario can produce a different break-even point.
This makes the calculation useful as a planning tool rather than simply a financial formula.
Limitations of Break-Even Analysis
Break-even analysis generally assumes a relatively stable relationship between selling price, variable cost, fixed cost, and sales volume.
Real businesses can be more complicated.
For example:
- Prices may change at different sales volumes.
- Suppliers may offer volume discounts.
- Fixed costs may increase after reaching capacity.
- Multiple products can have different margins.
- Customer demand can change.
- Sales may be seasonal.
- Taxes and financing costs may affect actual profitability.
- Production capacity may limit sales.
For businesses selling multiple products, a simple single-product break-even calculation may not accurately represent the overall business unless an appropriate sales mix is assumed.
Therefore, break-even analysis should generally be viewed as a planning model rather than a guarantee of future financial performance.
Frequently Asked Questions
What is the break-even point?
The break-even point is the sales level at which total revenue equals total costs. At this point, the business has neither a profit nor a loss.
What is the basic break-even formula?
The basic formula is:
Break-Even Units = Fixed Costs ÷ (Selling Price − Variable Cost per Unit)
What happens when fixed costs increase?
If the contribution margin stays unchanged, higher fixed costs increase the number of units that must be sold to reach break-even.
What happens when variable costs increase?
Higher variable costs reduce the contribution margin per unit, generally increasing the sales volume required to reach break-even.
Is break-even the same as profitability?
No. Break-even represents zero profit. A business becomes profitable when revenue exceeds the costs included in the analysis.
Why is contribution margin important?
Contribution margin shows how much each sale contributes toward covering fixed costs and eventually generating profit.
Can break-even analysis be used for services?
Yes. Instead of units, a service business can use billable hours, projects, subscriptions, clients, or other measurable sales units.